

Welcome to the Saturday PRO edition of How They Make Money.
Over 300,000 subscribers turn to us for business and investment insights.
In case you missed it:
Premium members get:
📊 Monthly reports: 200+ companies visualized.
📩 Tuesday articles: Exclusive deep dives and insights.
📚 Access to our archive: Hundreds of business breakdowns.
PRO members get everything PLUS:
📩 Saturday PRO reports: Timely insights on the latest earnings.
Today at a glance:
🔬 ASML: Demand Reaches 2030
💊 J&J: MedTech Needs Work
💼 UnitedHealth: Turnaround Broadens
🇺🇸 Bank of America: Fine Masks NII Growth
👔 Morgan Stanley: IPOs Feed Wealth
📈 BlackRock: Fee Growth Hits 11%
🏦 Schwab: Lending Boom
🍕 Domino’s: Orders Up, Check Down

1. 🔬 ASML: Demand Reaches 2030
ASML’s Q3 revenue surged 55% Y/Y to a record €11.7 billion (€70 million miss), while GAAP EPS reached €12.93 (€2.14 beat). The EPS beat was partly flattered by a €0.5 billion valuation gain on ASML’s investment in Mistral AI, but the underlying quarter was still impressive. Gross margin reached a record 57%, well above guidance, as high-margin upgrades pushed Installed Base Management sales to €3.3 billion.
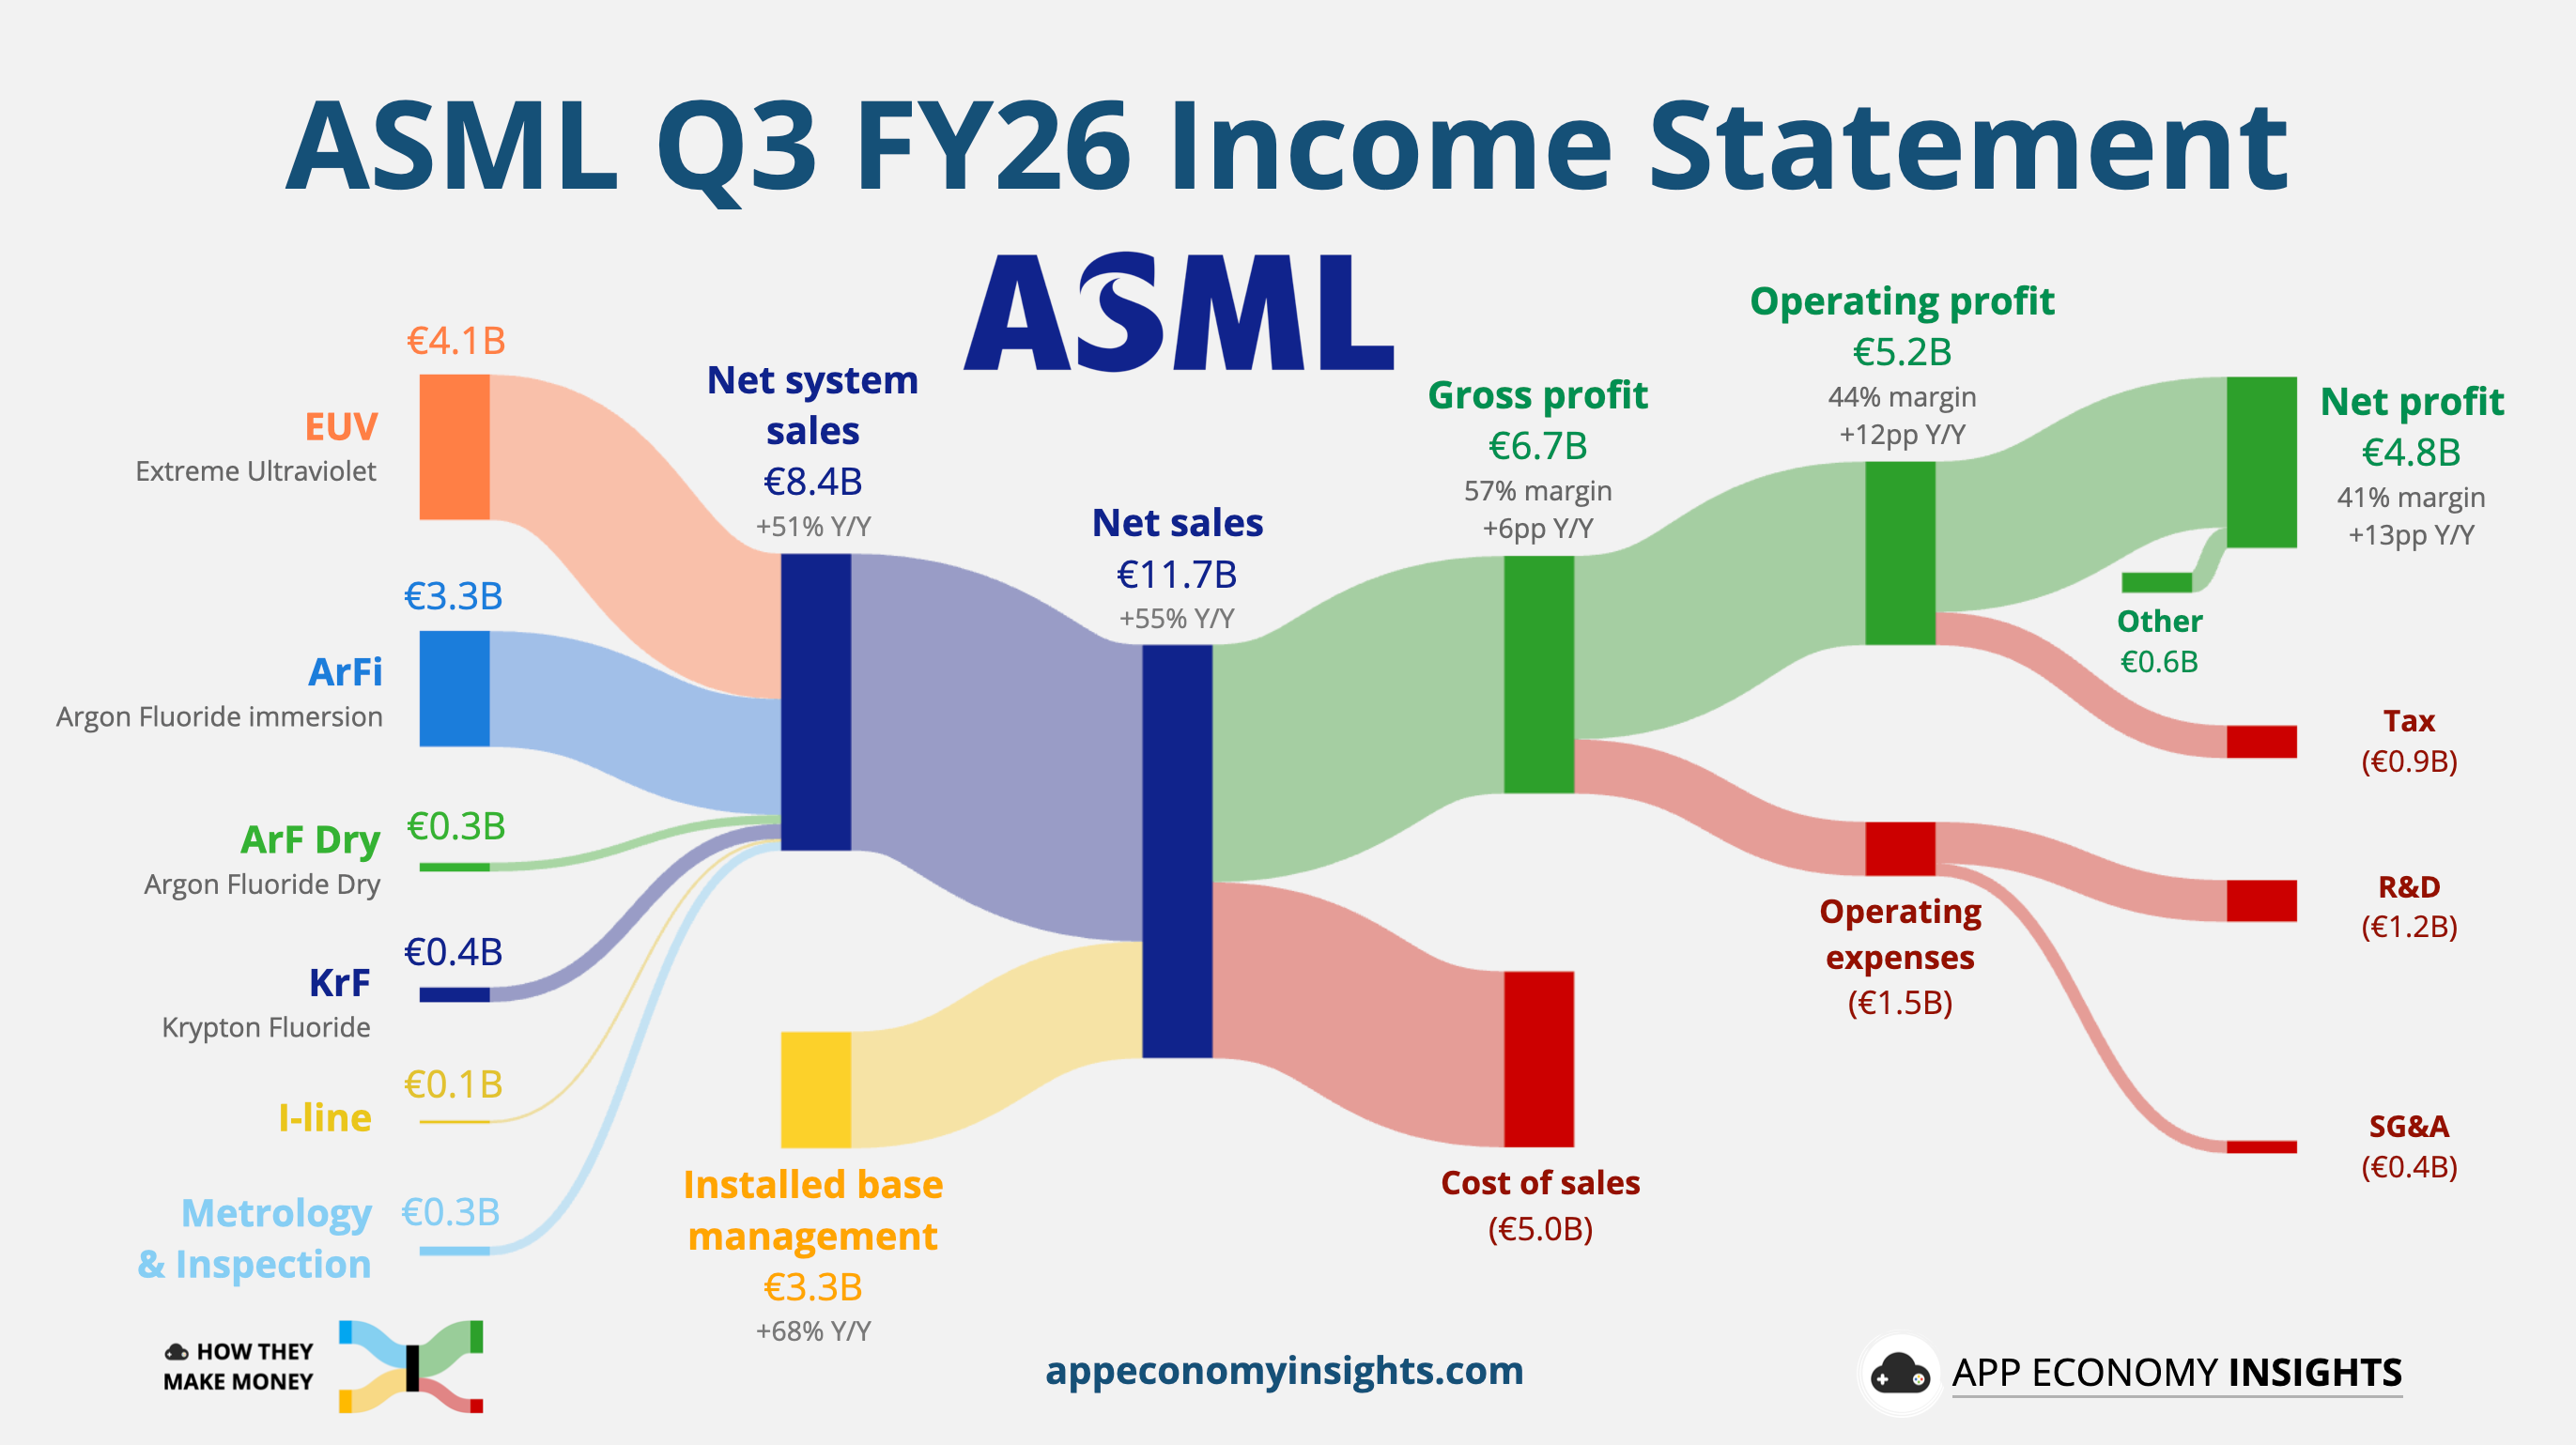
The biggest insight was how far out the AI capacity cycle has moved. Customers are increasingly placing orders for 2028 and asking ASML to accept orders for 2029 and even 2030. Management now says its currently planned supply will not fully meet demand in either 2027 or 2028. That is remarkable because ASML already planned to increase Low-NA EUV and immersion DUV capacity by roughly 30% in 2027, followed by another ~30% increase in 2028. It is now exploring an even larger ramp in 2028.
The demand is increasingly broad:
Memory system sales are expected to grow ~75% in FY26, driven largely by DRAM capacity and greater EUV adoption.
Advanced logic is growing more than 25%, even though total logic growth is closer to 10%.
EUV sales should grow more than 45% this year, while Installed Base Management is now expected to grow roughly 50%.
ASML shipped 113 new lithography systems in Q3, up from 86 in Q2.
ASML has now secured price increases on some of its most critical high-volume tools. Management expects the benefit to begin showing up in 2027 and become fully visible in 2028. Management stressed this isn’t opportunistic annual repricing, but it does confirm that ASML can capture more of the value its bottleneck technology creates.
High-NA is moving closer to actual production. Intel has now processed more than one million wafers using High-NA, Samsung plans high-volume adoption in 2028, and TSMC now targets 2030. ASML expects High-NA usage to expand node by node as customers validate the economics.
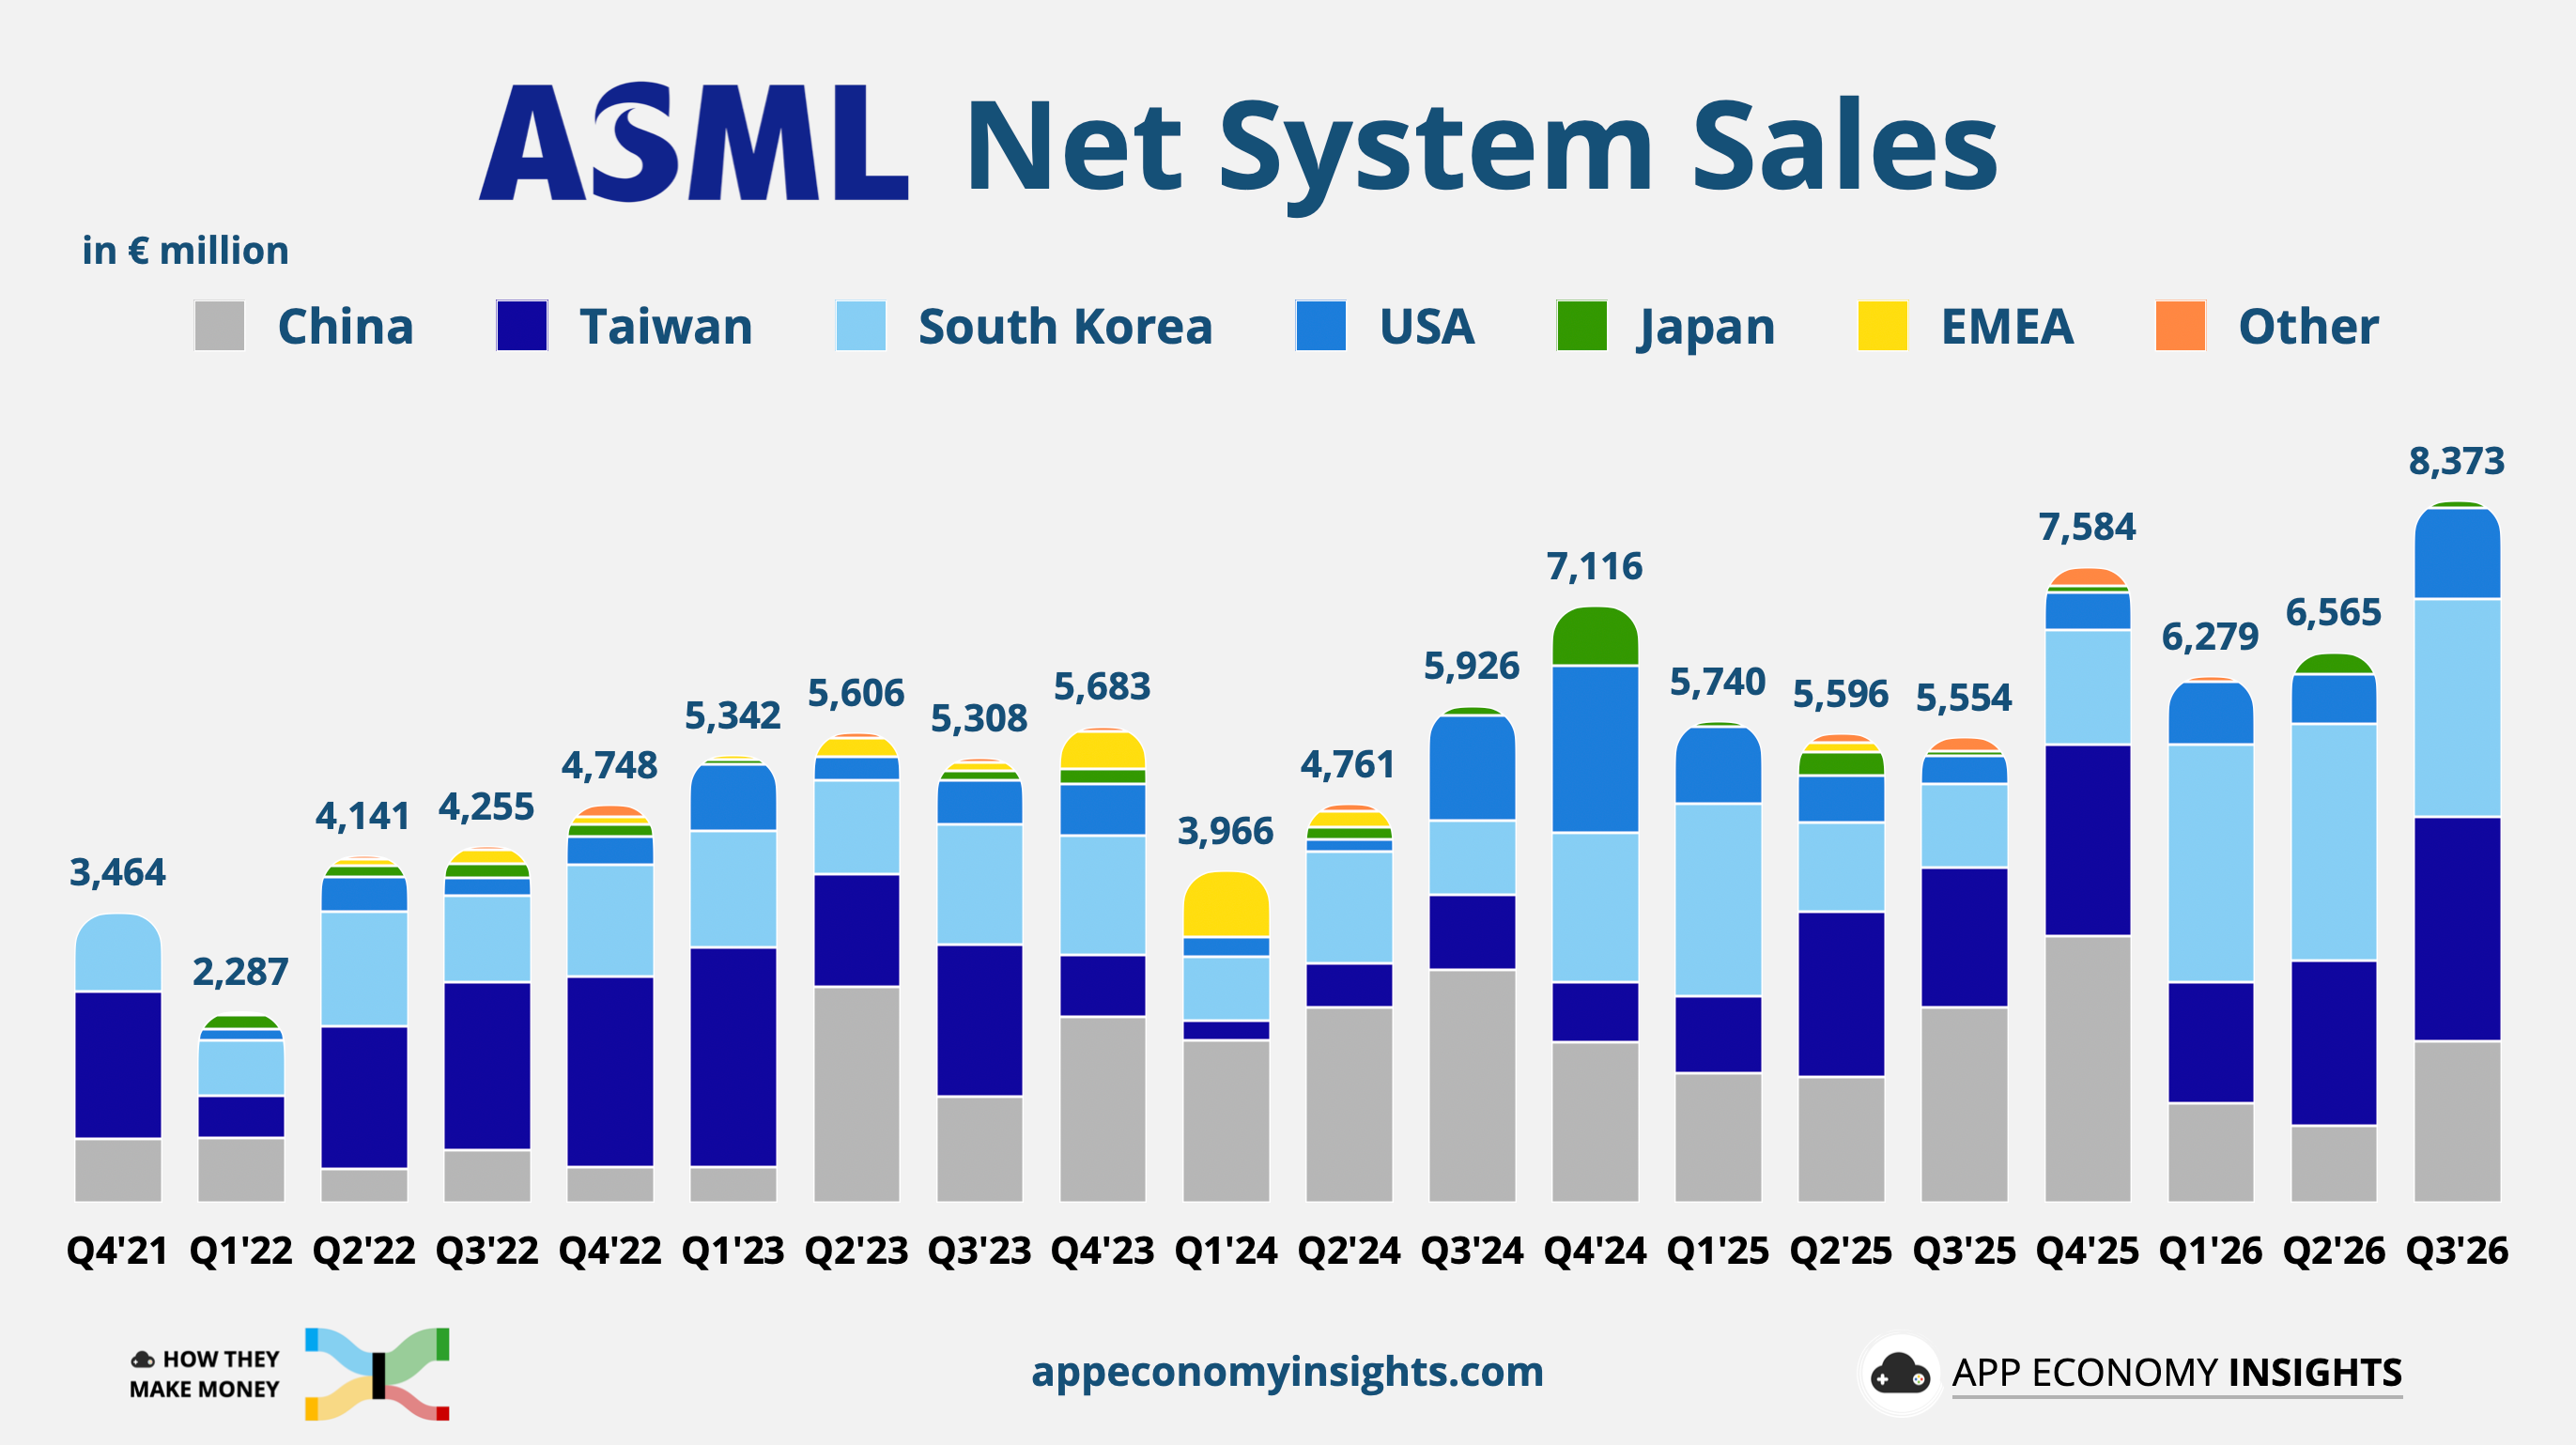
China remains the geopolitical wildcard. It represented 23% of Q3 system sales, while ASML still expects roughly 20% of full-year revenue from China. Management argues underlying Chinese demand remains strong, but further restrictions on immersion DUV could eventually accelerate development of domestic alternatives.
ASML raised FY26 revenue guidance again to €44–€45 billion (from €43–€45 billion) and now expects a gross margin of roughly 56%.
Takeaway: ASML has moved from ramping capacity to figuring out how much further it can stretch the supply chain. Customers are already signaling demand into 2030, while pricing increases and High-NA add further upside. Now it’s about ASML’s ability to build enough machines.