

Welcome to the Premium edition of How They Make Money.
Over 300,000 subscribers turn to us for business and investment insights.
In case you missed it:

Amazon CEO Andy Jassy believes AWS can become a $1 trillion annual revenue business within five to ten years.
That’s more than five times its current $184 billion run rate. AWS growth accelerated to 39% in Q3, backlog reached $578 billion, and Jassy now expects growth above 40% in both 2027 and 2028.
But the price tag is mind-boggling. Amazon’s trailing free cash flow plunged to negative $42 billion, while CapEx is expected to rise meaningfully above this year’s $220 billion in 2027.
Jassy remains undeterred:
“We can fund this plan. I think it will forever change the size of Amazon.”
The challenge is turning this unprecedented spending into lasting cash flow and attractive returns for shareholders.
Now let’s see what stood out this quarter.
Today at a glance:
Amazon Q3 FY26.
The AWS flywheel.
Key quotes from the call.
What to watch moving forward.

1. Amazon Q3 FY26
Income statement:
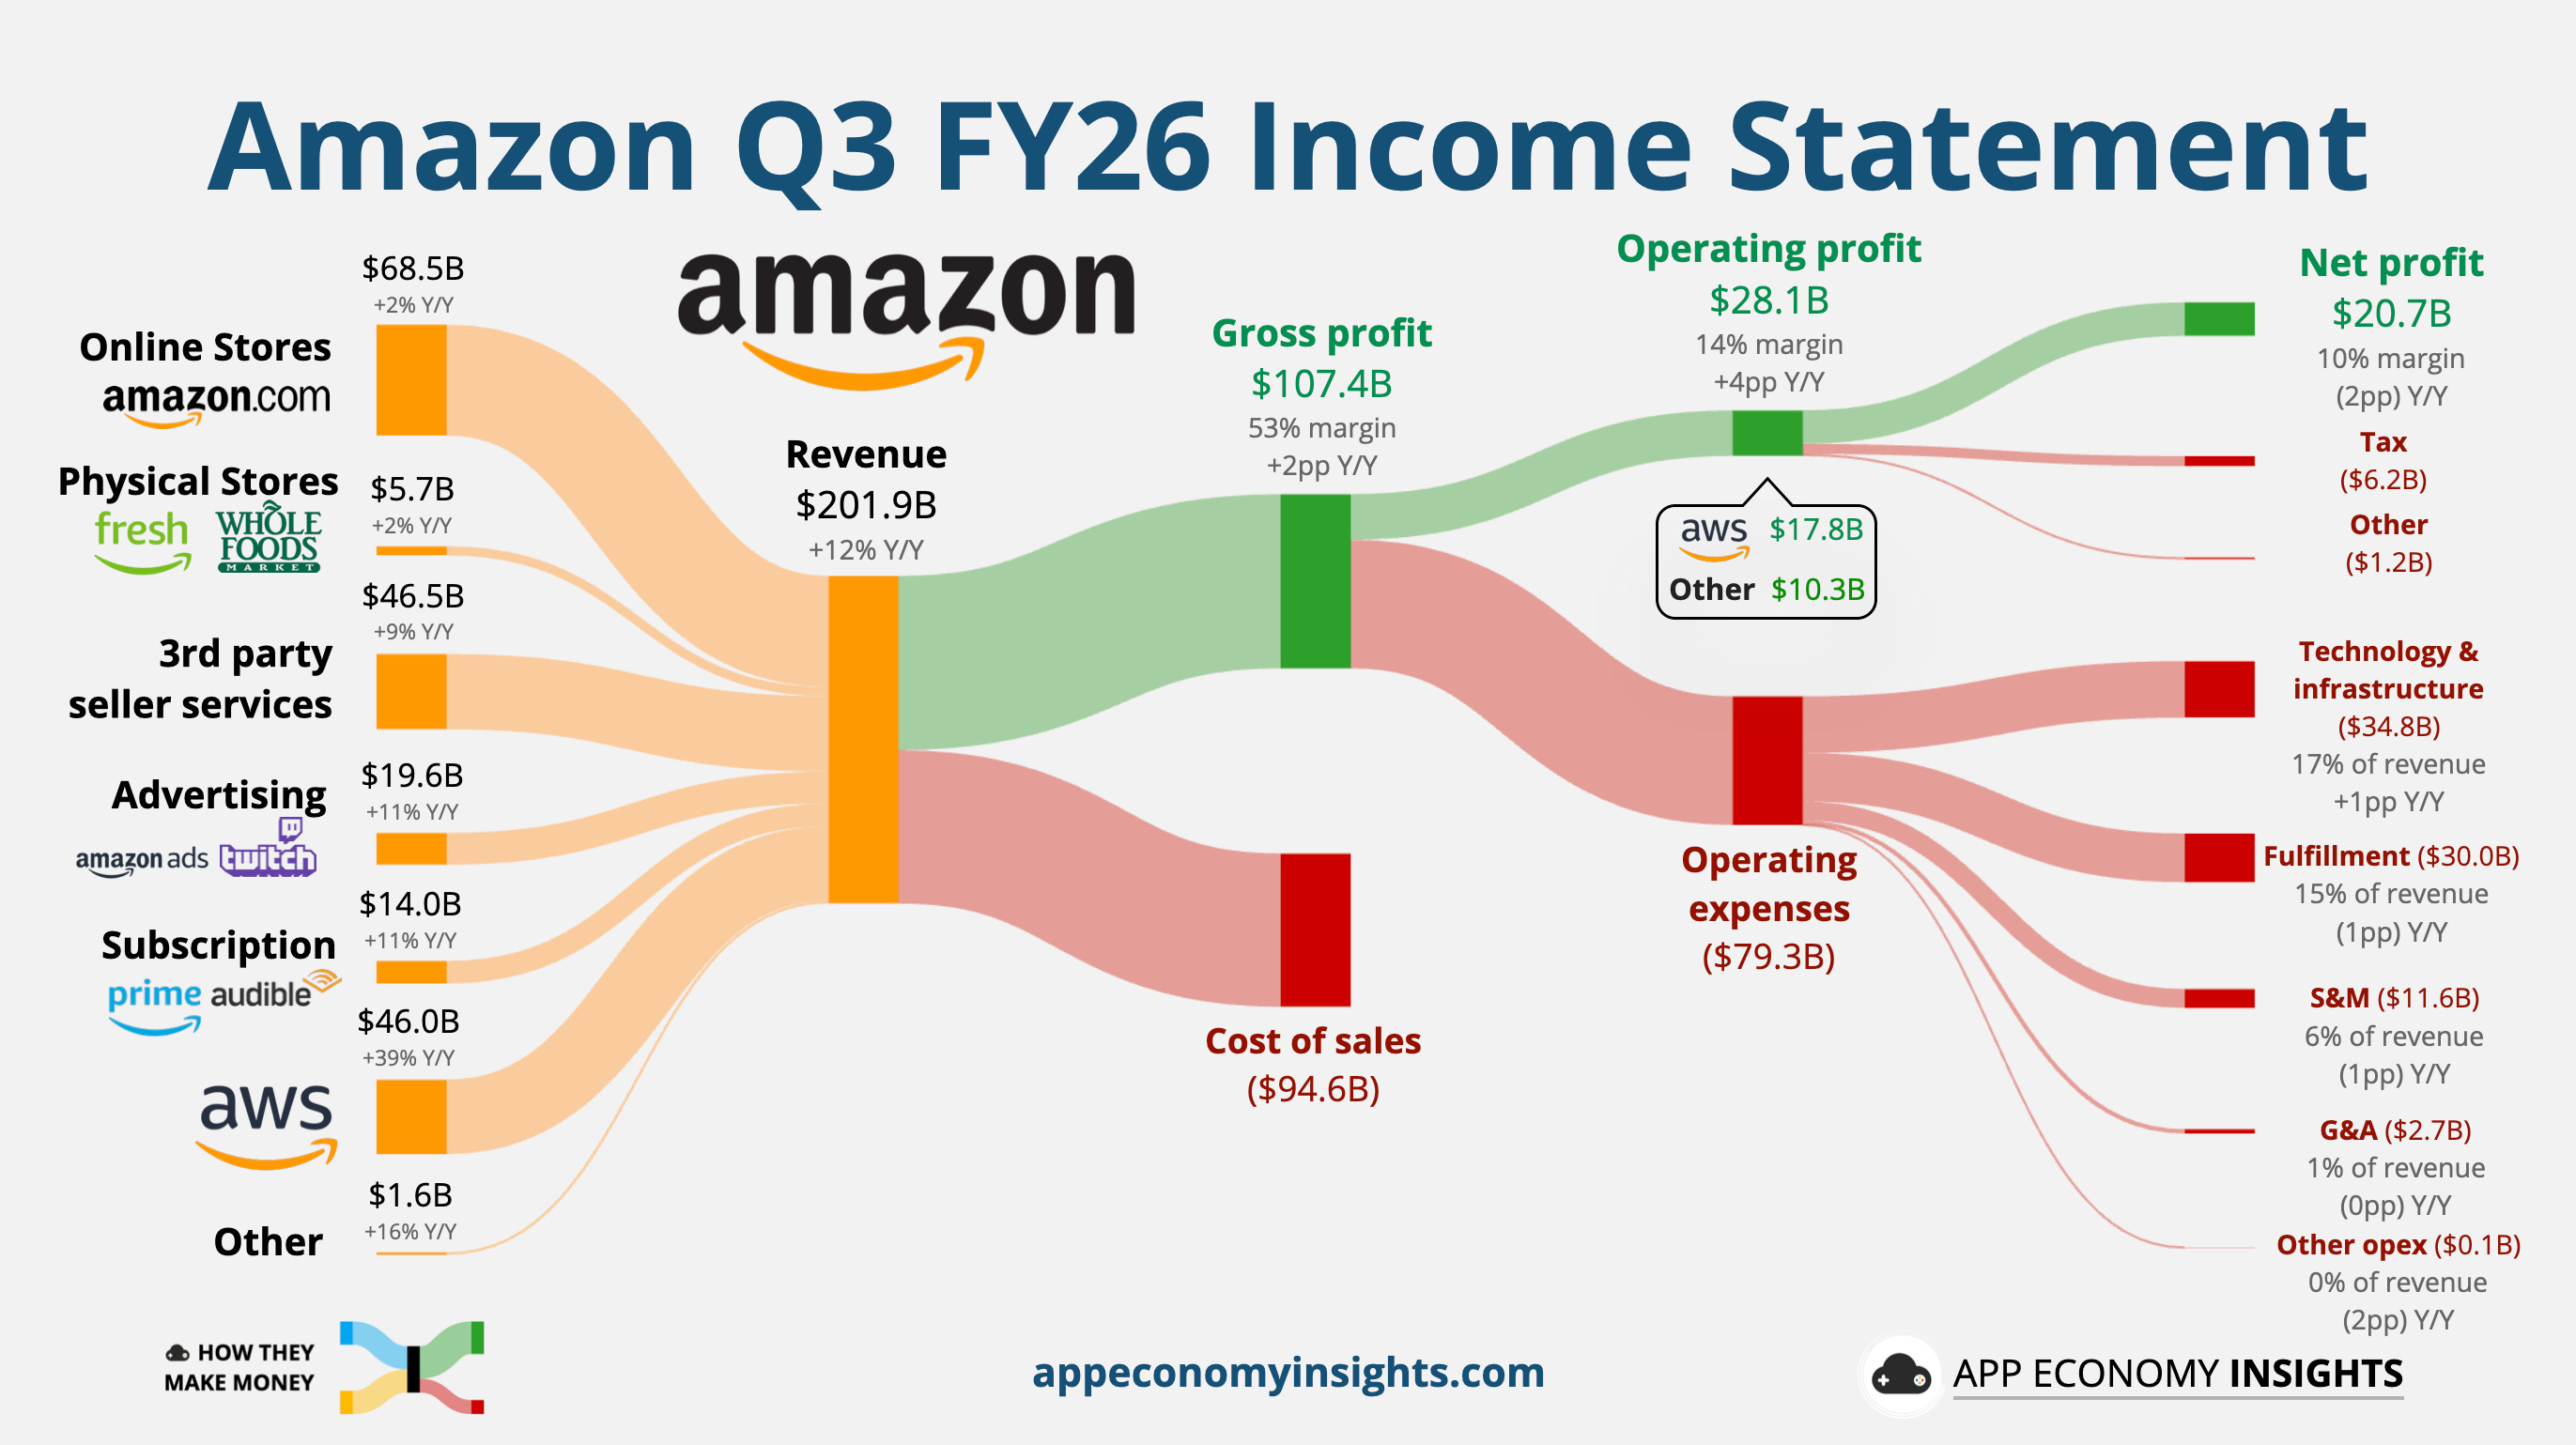
Revenue rose 12% Y/Y to $201.9 billion ($0.4 billion miss)
Gross margin was 53% (+2pp Y/Y).
Operating margin reached a record 14% (+4pp Y/Y).
AWS: 39% margin (+4pp Y/Y).
North America: 8% margin (+3pp Y/Y).
International: 4% margin (+1pp Y/Y).
Operating income surged 61% Y/Y to $28.1 billion. However, the prior-year quarter included $4.3 billion in FTC settlement and severance charges. Excluding these, operating income grew approximately 29%.
Net profit fell 2% Y/Y to $20.7 billion. The comparison was affected by a $9.5 billion non-operating gain from Anthropic in Q3 FY25.
Cash flow:
Operating cash flow TTM rose 29% Y/Y to $168.3 billion.
Free cash flow TTM deteriorated to negative $42.4 billion, compared with negative $7.6 billion in Q2, as CapEx surged 82% Y/Y to $210.7 billion TTM.
Balance sheet:
Cash, cash equivalents, and marketable securities: $114 billion.
Long-term debt: $173 billion, up from $129 billion in Q2.
Q4 FY26 Guidance:
Revenue growth of 12% to 16% Y/Y.
Operating income of approximately $31 billion, or +24% Y/Y at the midpoint.
So, what to make of all this?
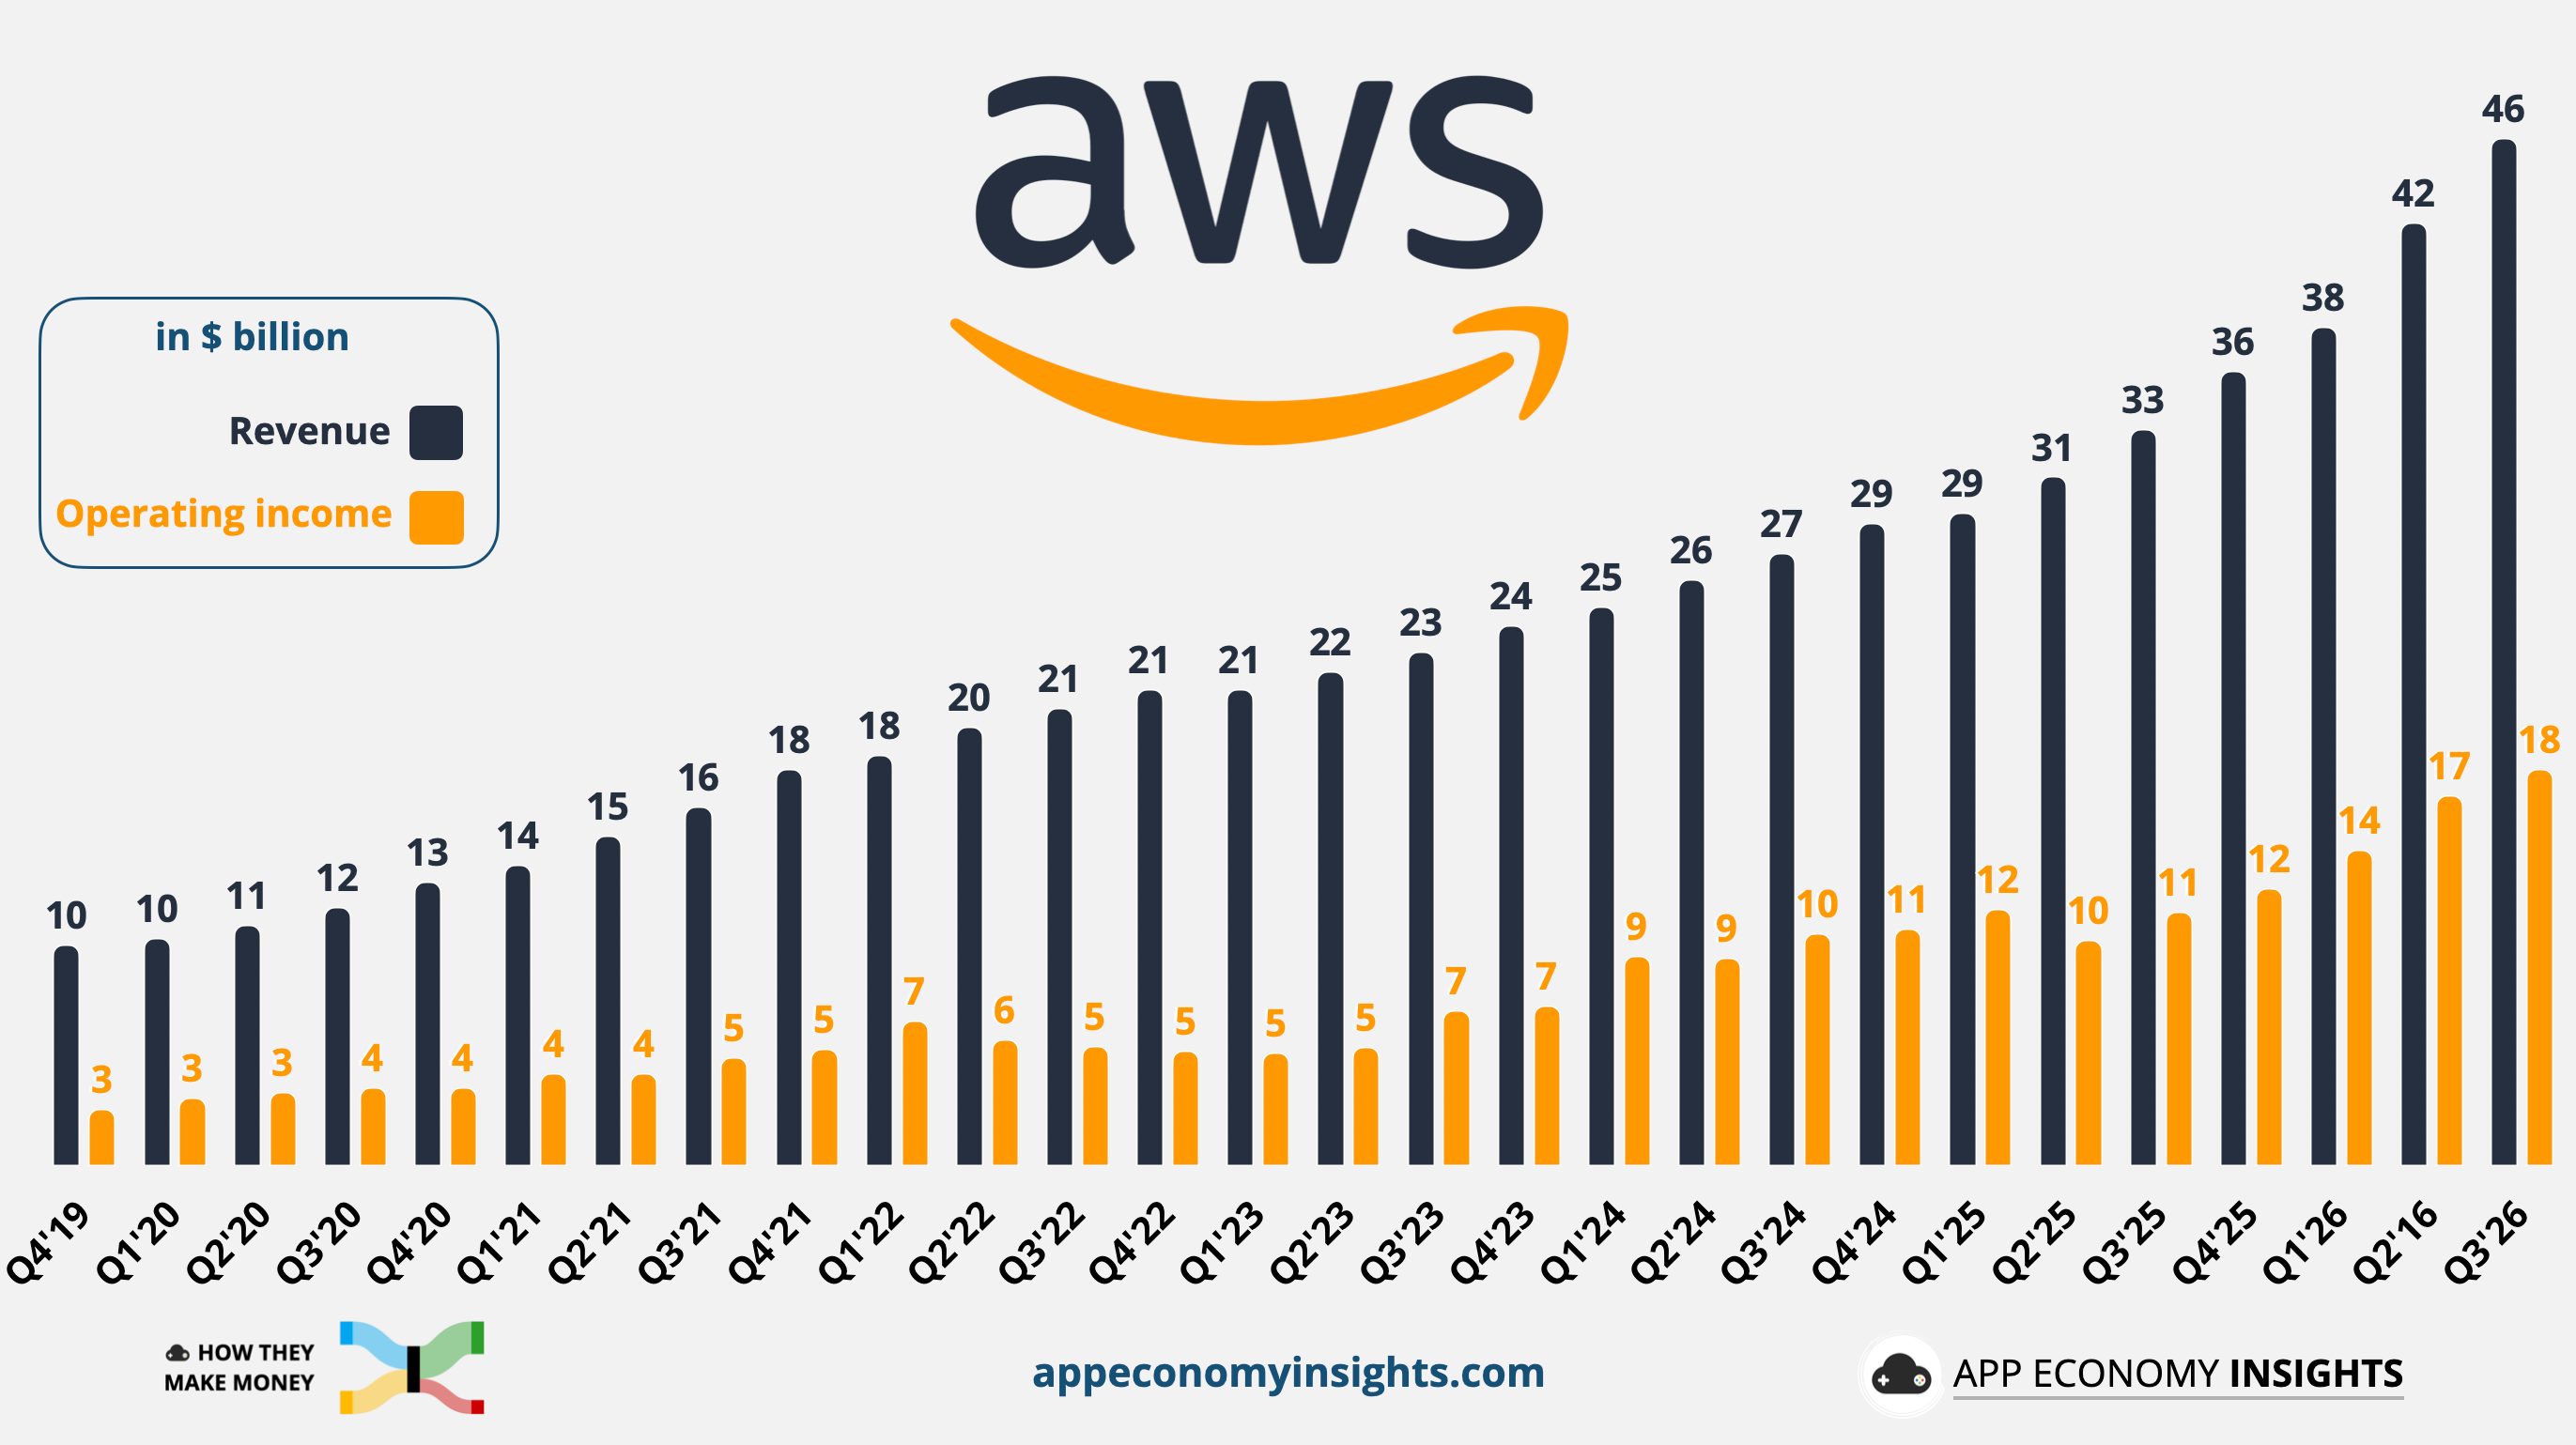
☁️ AWS accelerates again: Revenue grew 39% Y/Y to $46.0 billion, accelerating for the sixth consecutive quarter. Operating income surged 55% to $17.8 billion. Backlog climbed to $578 billion, up from $496 billion in Q2. AWS added $3.8 billion in sequential revenue despite capacity constraints, and management says core compute and storage are growing at their fastest rates in years.
💵 The AI bill keeps growing: Amazon spent $75.9 billion in cash CapEx in Q3 alone, compared with $42.4 billion in operating cash flow, resulting in approximately $33.5 billion in negative quarterly free cash flow. The company maintained its $220 billion CapEx forecast for 2026, but Jassy expects to spend meaningfully more in 2027. Amazon’s investments are accelerating faster than its ability to generate cash internally.

📦 Retail margins improved, with a caveat: North America revenue grew 6%, International grew 5%, and worldwide paid units increased 12%. Reported growth was distorted by Prime Day moving into Q2, reducing companywide revenue growth by approximately four percentage points. Excluding last year's $2.5 billion FTC settlement charge, North America margin expansion was less than one percentage point. Meanwhile, shipping costs grew 11%, slightly below unit growth despite higher fuel expenses.
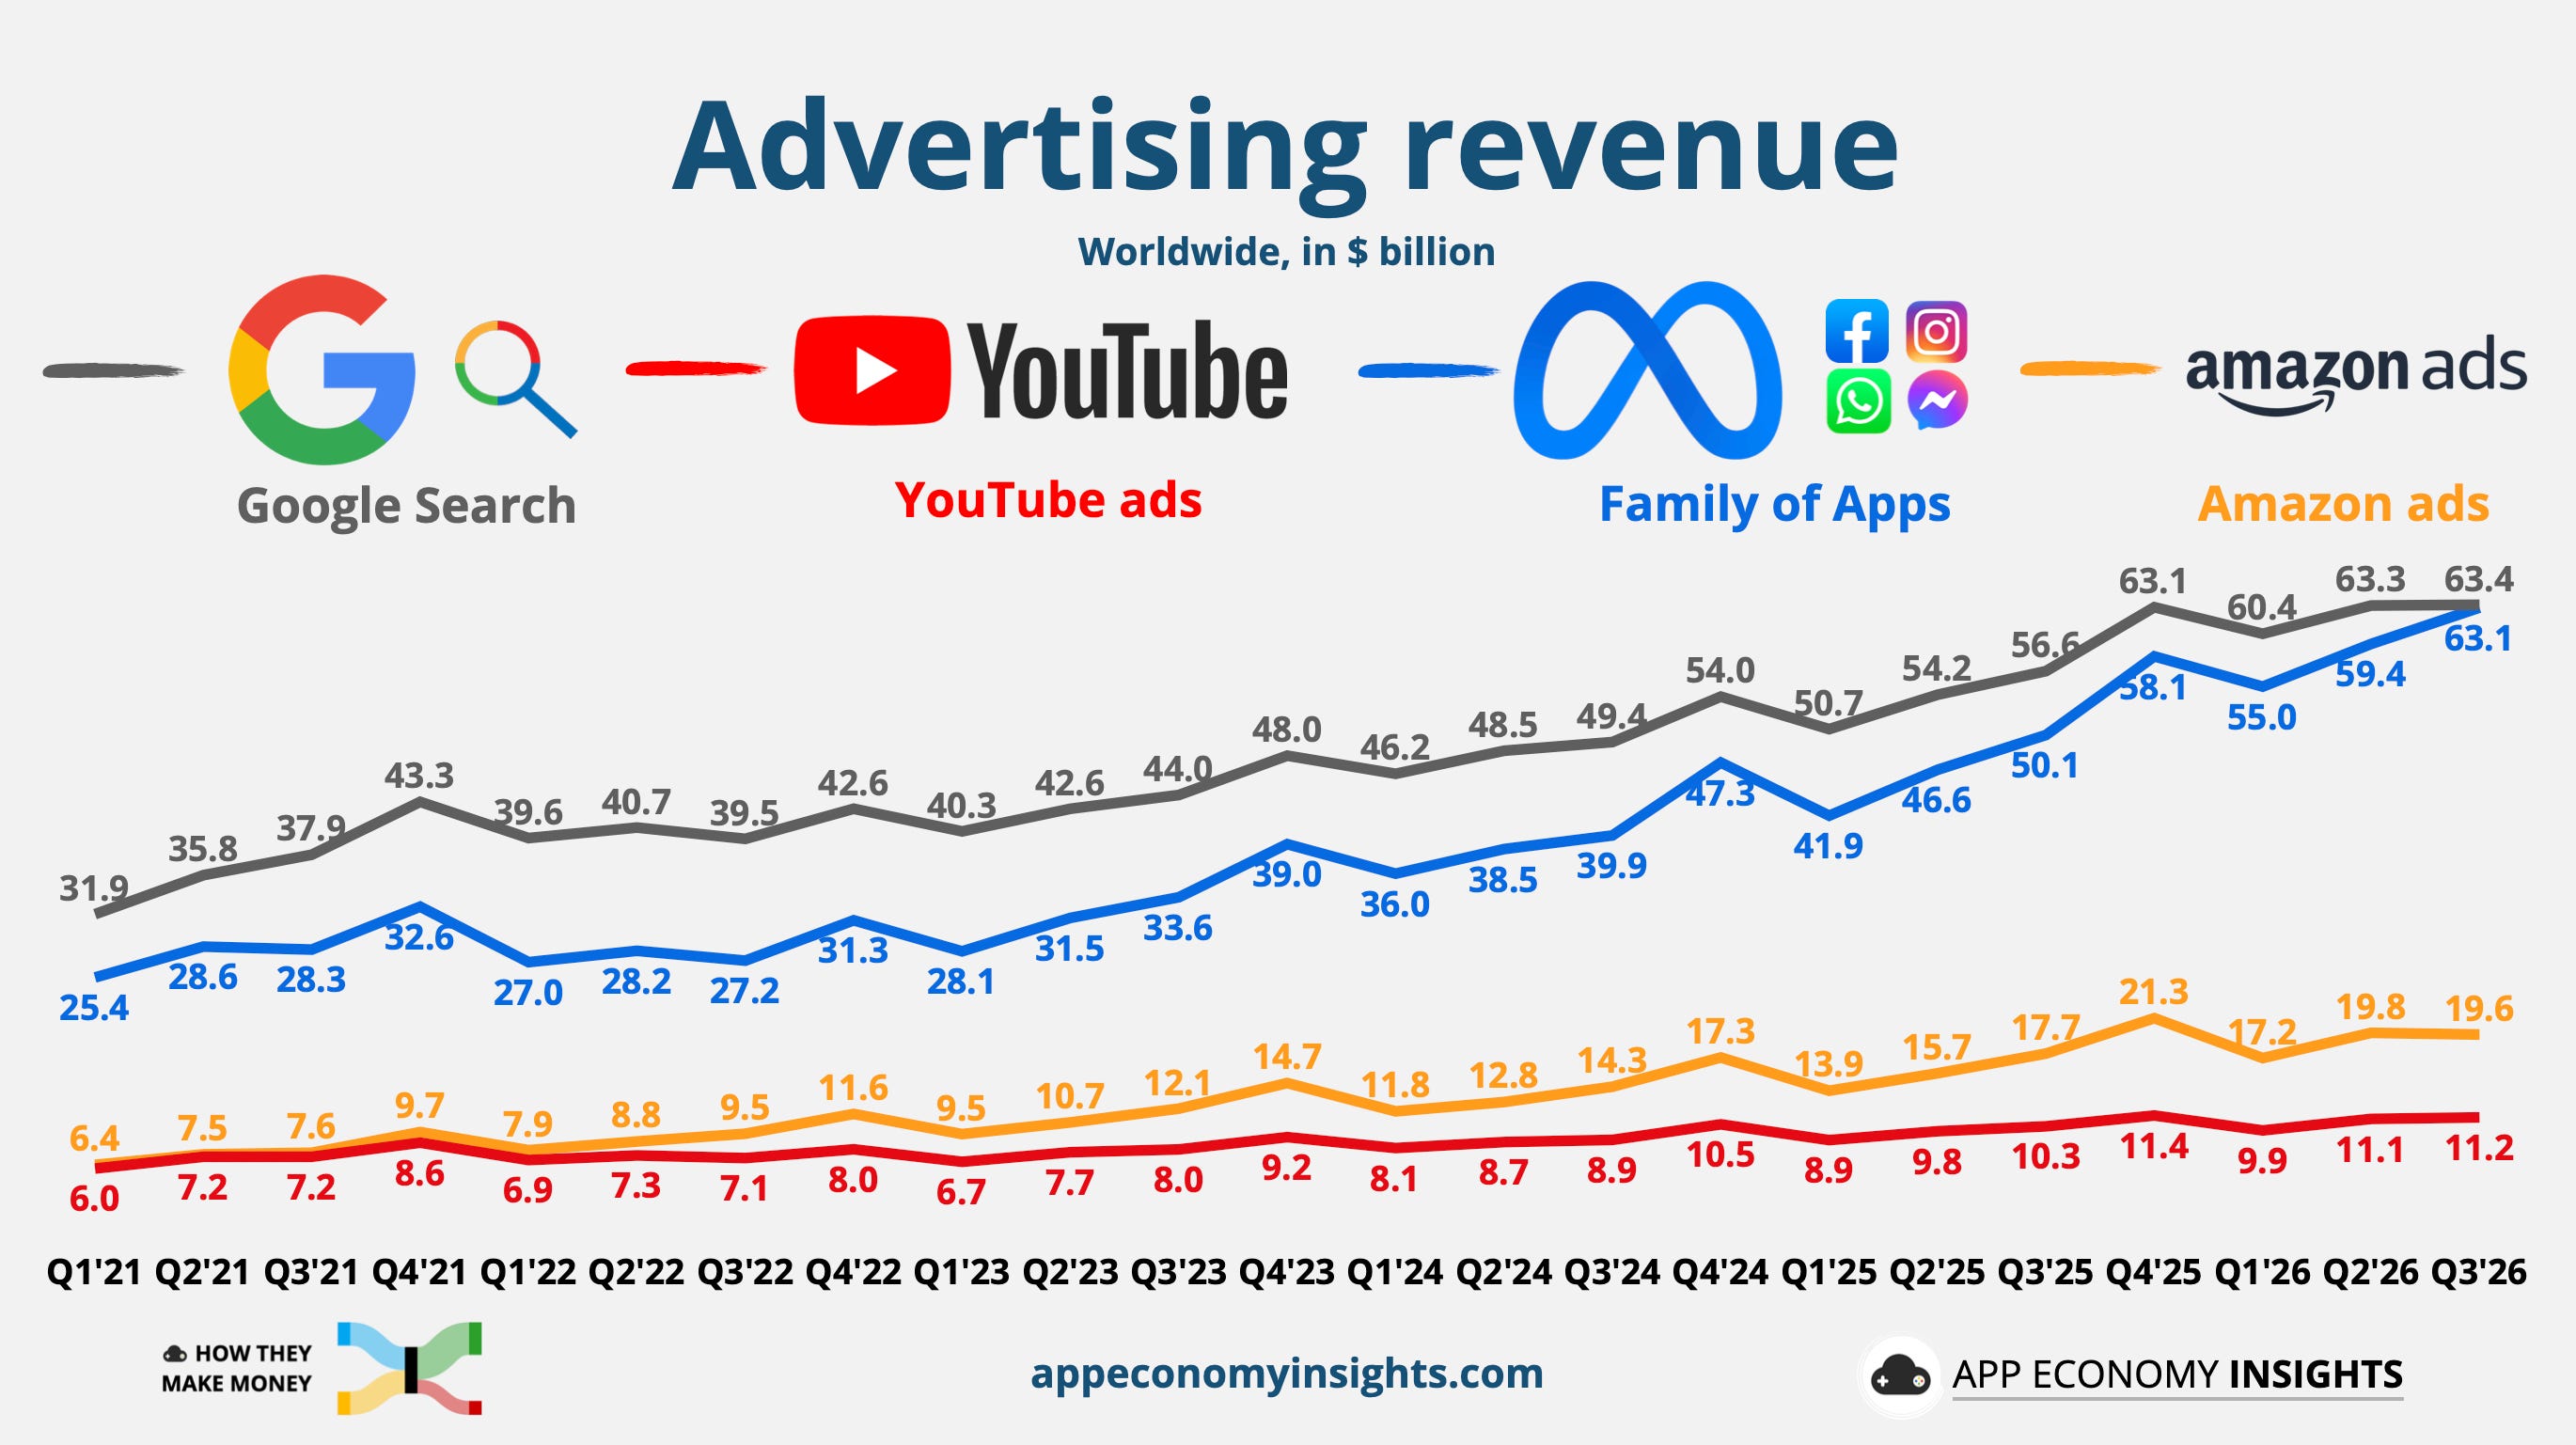
📢 Advertising hits a speed bump: Revenue grew just 12% Y/Y in constant currency (11% reported) to $19.6 billion, down sharply from 26% growth in Q2. The Prime Day shift explains roughly 8.5 percentage points of the slowdown from Q2 to Q3, with NBA scheduling and tougher comparisons also contributing. Management expects growth to recover to the high teens in Q4, suggesting the slowdown may be largely temporary.
🔮 Guidance is slightly softer than expected: Q4 revenue guidance implies $243.5 billion at the midpoint, roughly $1 billion below consensus. Operating income is expected to grow 24% Y/Y to $31 billion, although Amazon Leo will remain a drag as certain production and launch costs won’t begin to be capitalized until Q1 2027. The outlook suggests continued operating profit growth despite the enormous infrastructure buildout.