

Welcome to the Saturday PRO edition of How They Make Money.
Over 300,000 subscribers turn to us for business and investment insights.
In case you missed it:
Premium members get:
📊 Monthly reports: 200+ companies visualized.
📩 Tuesday articles: Exclusive deep dives and insights.
📚 Access to our archive: Hundreds of business breakdowns.
PRO members get everything PLUS:
📩 Saturday PRO reports: Timely insights on the latest earnings.
Today at a glance:
🥤 PepsiCo: International Takes Over
🛩️ Delta: Fuel Eats the Upside
🍺 Constellation: SpikedAde Joins the Mix
🌿 Tilray: BrewDog Carries Growth

1. 🥤 PepsiCo: International Takes Over
PepsiCo’s Q3 revenue rose 6% Y/Y to $25.3 billion ($310 million beat), with core EPS of $2.34 ($0.04 beat). Organic revenue growth accelerated to 3.1%, its fastest pace since late 2023, helped by 3% beverage volume growth and 1% food volume growth.
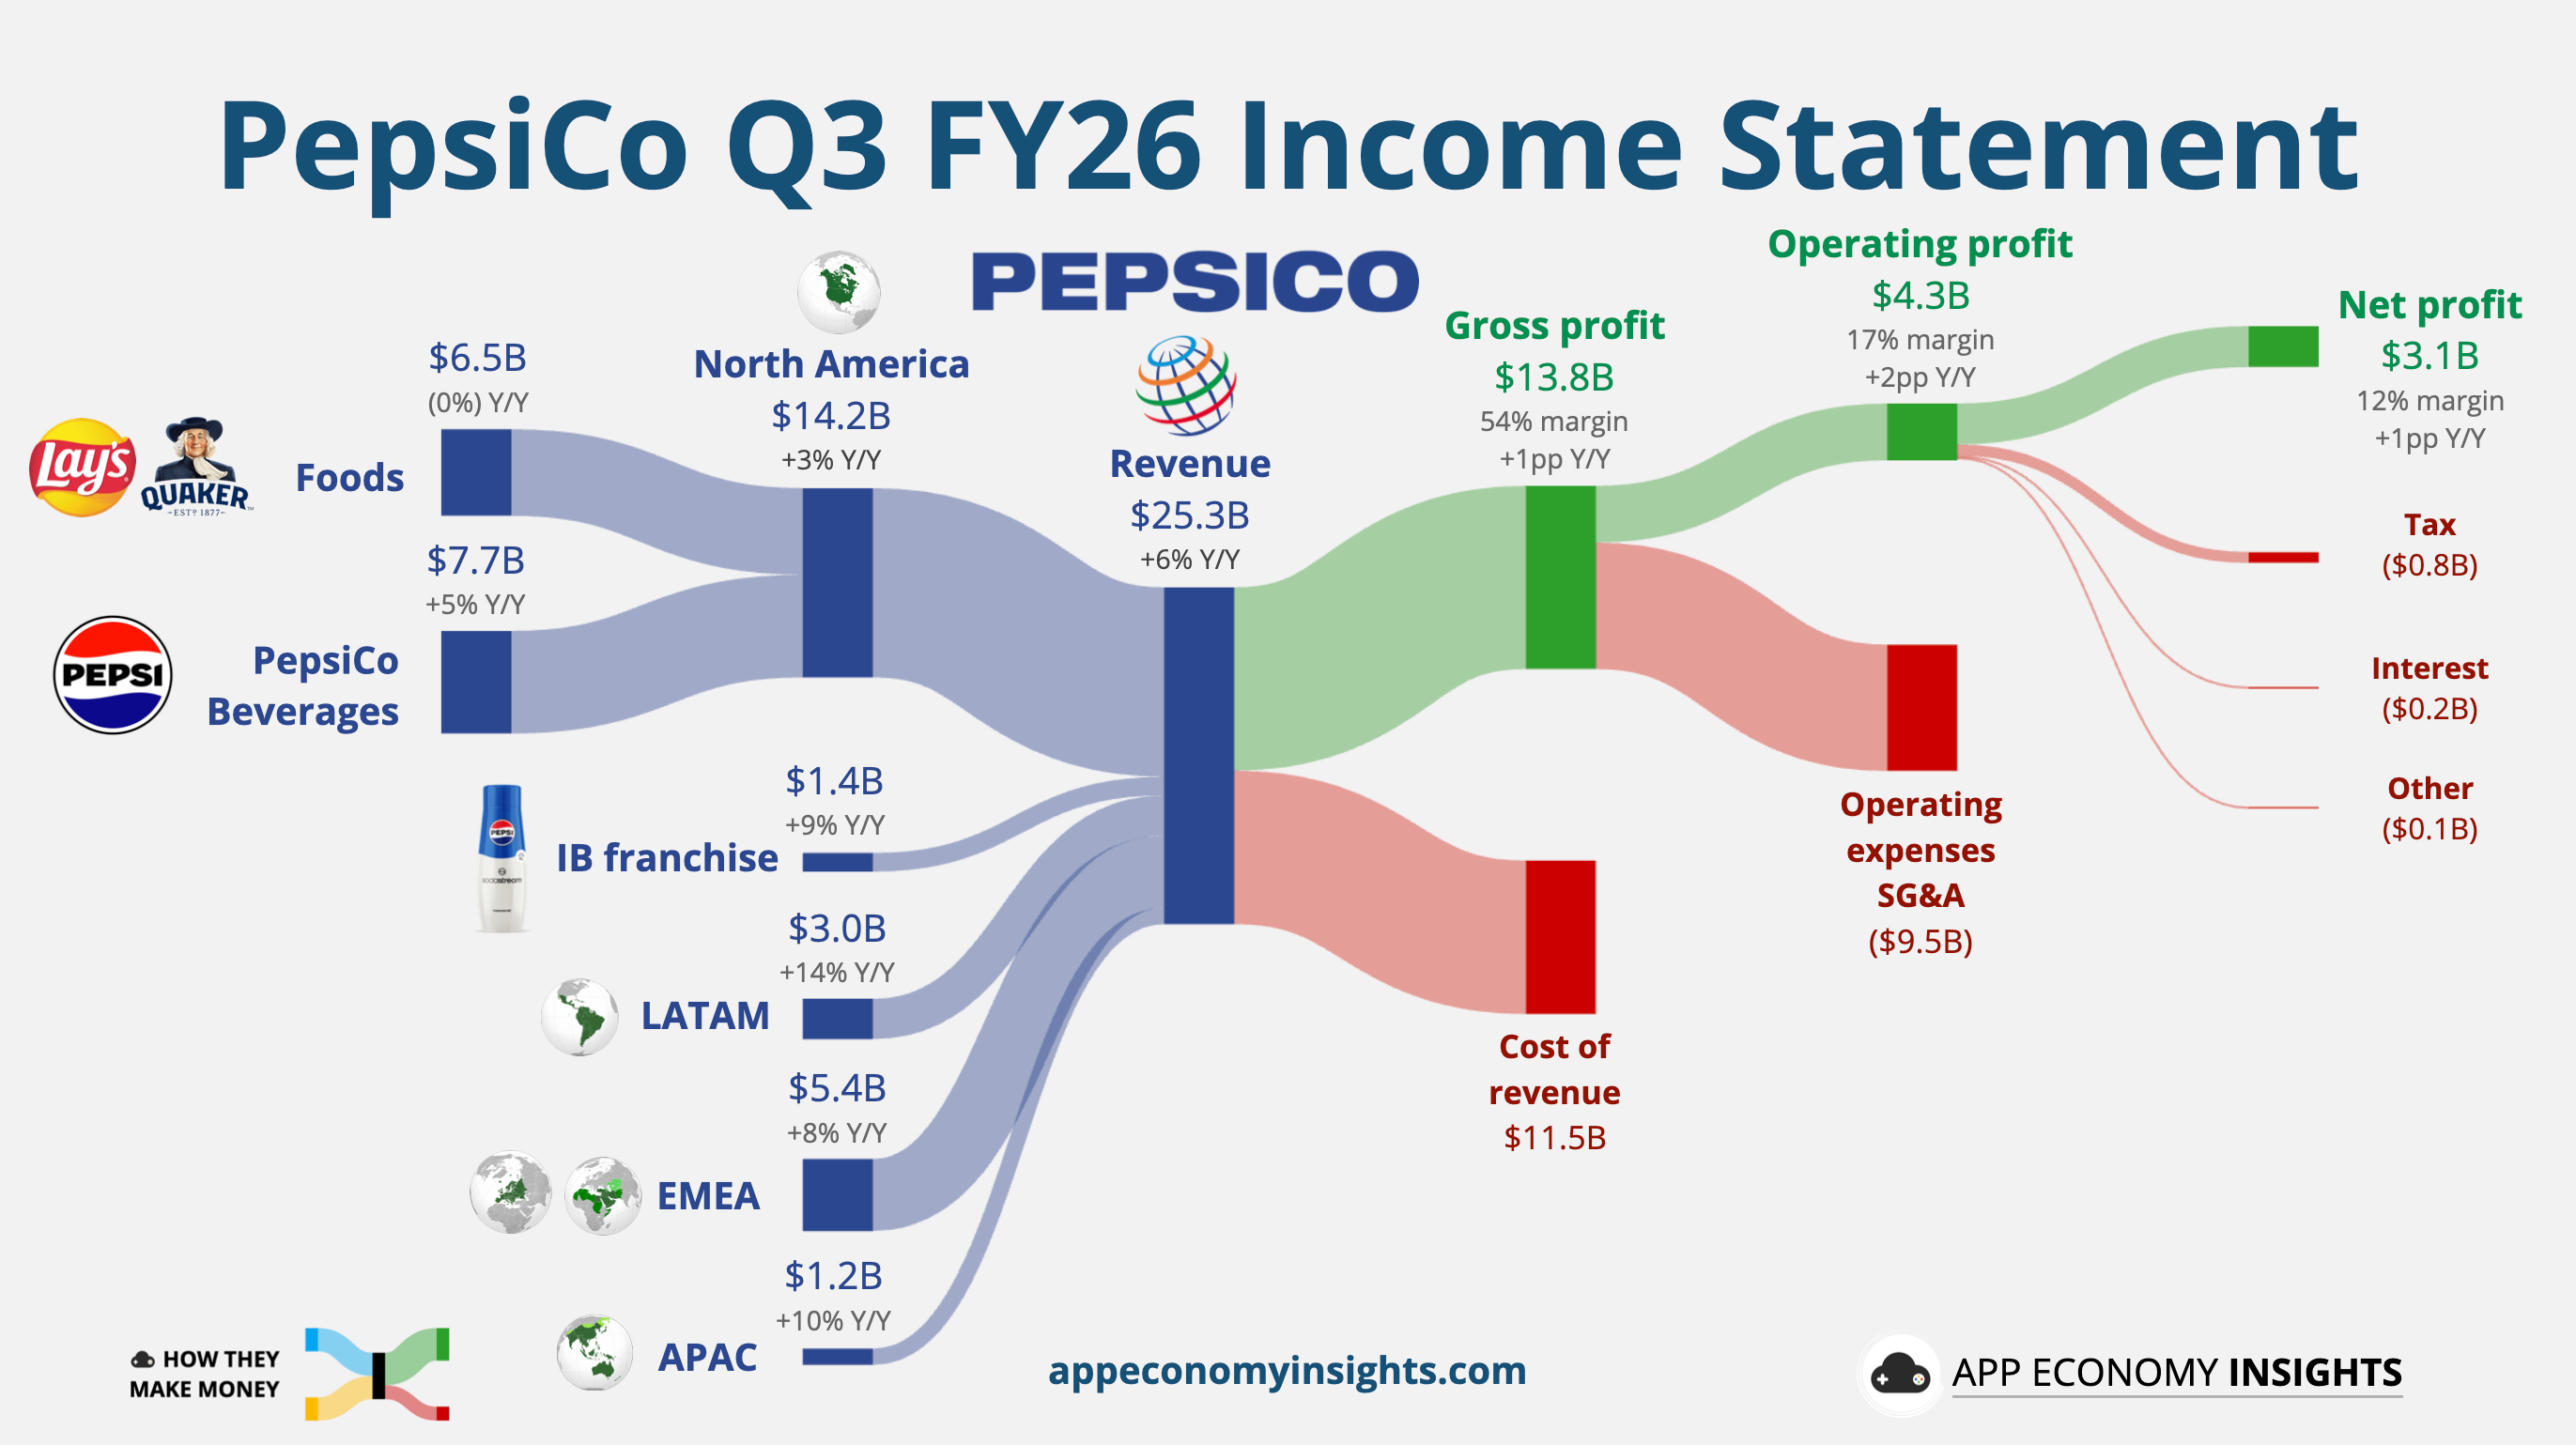
The divergence between North America and the rest of the world keeps widening:
International organic revenue grew ~8%, with EMEA up 9%. International now generates roughly 45% of PepsiCo’s profit year-to-date.
North American Foods sales were flat, though volumes improved to low-single-digit growth after last year's declines.
North American Beverages weakened, with CEO Ramon Laguarta admitting PepsiCo is “not competing well in soft drinks,” even as hydration and energy remain stronger.
GLP-1s and changing eating habits are pushing PepsiCo toward smaller portions and more protein- and fiber-focused products. Its “permissible” portfolio (better-for-you snacks) has already grown to roughly $3 billion, but it remains small relative to the traditional snack business under pressure.
PepsiCo also has an execution problem in its home market. Management plans to increase brand investment while cutting structural costs, and it is even open to selling more of its company-owned bottling operations to independent partners, making the business less capital-intensive.
Margins are getting harder to protect. Core operating profit grew 3%, but a $178 million tariff refund added roughly four percentage points to operating profit growth. Commodity costs are rising as hedges roll off, while PepsiCo is deliberately maintaining higher advertising spending to rebuild momentum.
PepsiCo now expects about 3% organic revenue growth in FY26, while cutting core constant-currency EPS growth to 2.5%–3.5% (from 4%–6%).
Takeaway: International is increasingly carrying PepsiCo while the North American turnaround takes longer than expected. With costs rising and US execution still uneven, management is moving beyond price tweaks toward a broader cost and operating-model reset.