

Welcome to the Saturday PRO edition of How They Make Money.
Over 300,000 subscribers turn to us for business and investment insights.
In case you missed it:
Premium members get:
📊 Monthly reports: 200+ companies visualized.
📩 Tuesday articles: Exclusive deep dives and insights.
📚 Access to our archive: Hundreds of business breakdowns.
PRO members get everything PLUS:
📩 Saturday PRO reports: Timely insights on the latest earnings.
Today at a glance:
🛒 Costco: Refunds Fund Price Cuts
🍪 General Mills: Innovation Gains Traction
🫒 Darden: Olive Garden Still Lags

1. 🛒 Costco: Refunds Fund Price Cuts
Costco Q4 revenue rose 11% Y/Y to $95.7 billion ($0.8 billion beat), while EPS increased 15% to $6.75. That included a $0.15 benefit from tariff refunds, so underlying EPS growth was closer to 12%. Comparable sales rose 9.4%, or 6.7% excluding gas and FX, essentially maintaining Q3’s 6.6% pace.
Fuel remained a tailwind, adding roughly 3 points to comps, but the core business was balanced. Adjusted traffic increased 3.3%, and average ticket rose 3.3%. Digitally enabled comps grew another 20%, with annual digitally enabled sales now exceeding $33 billion (~11% of Costco’s overall FY26 revenue).
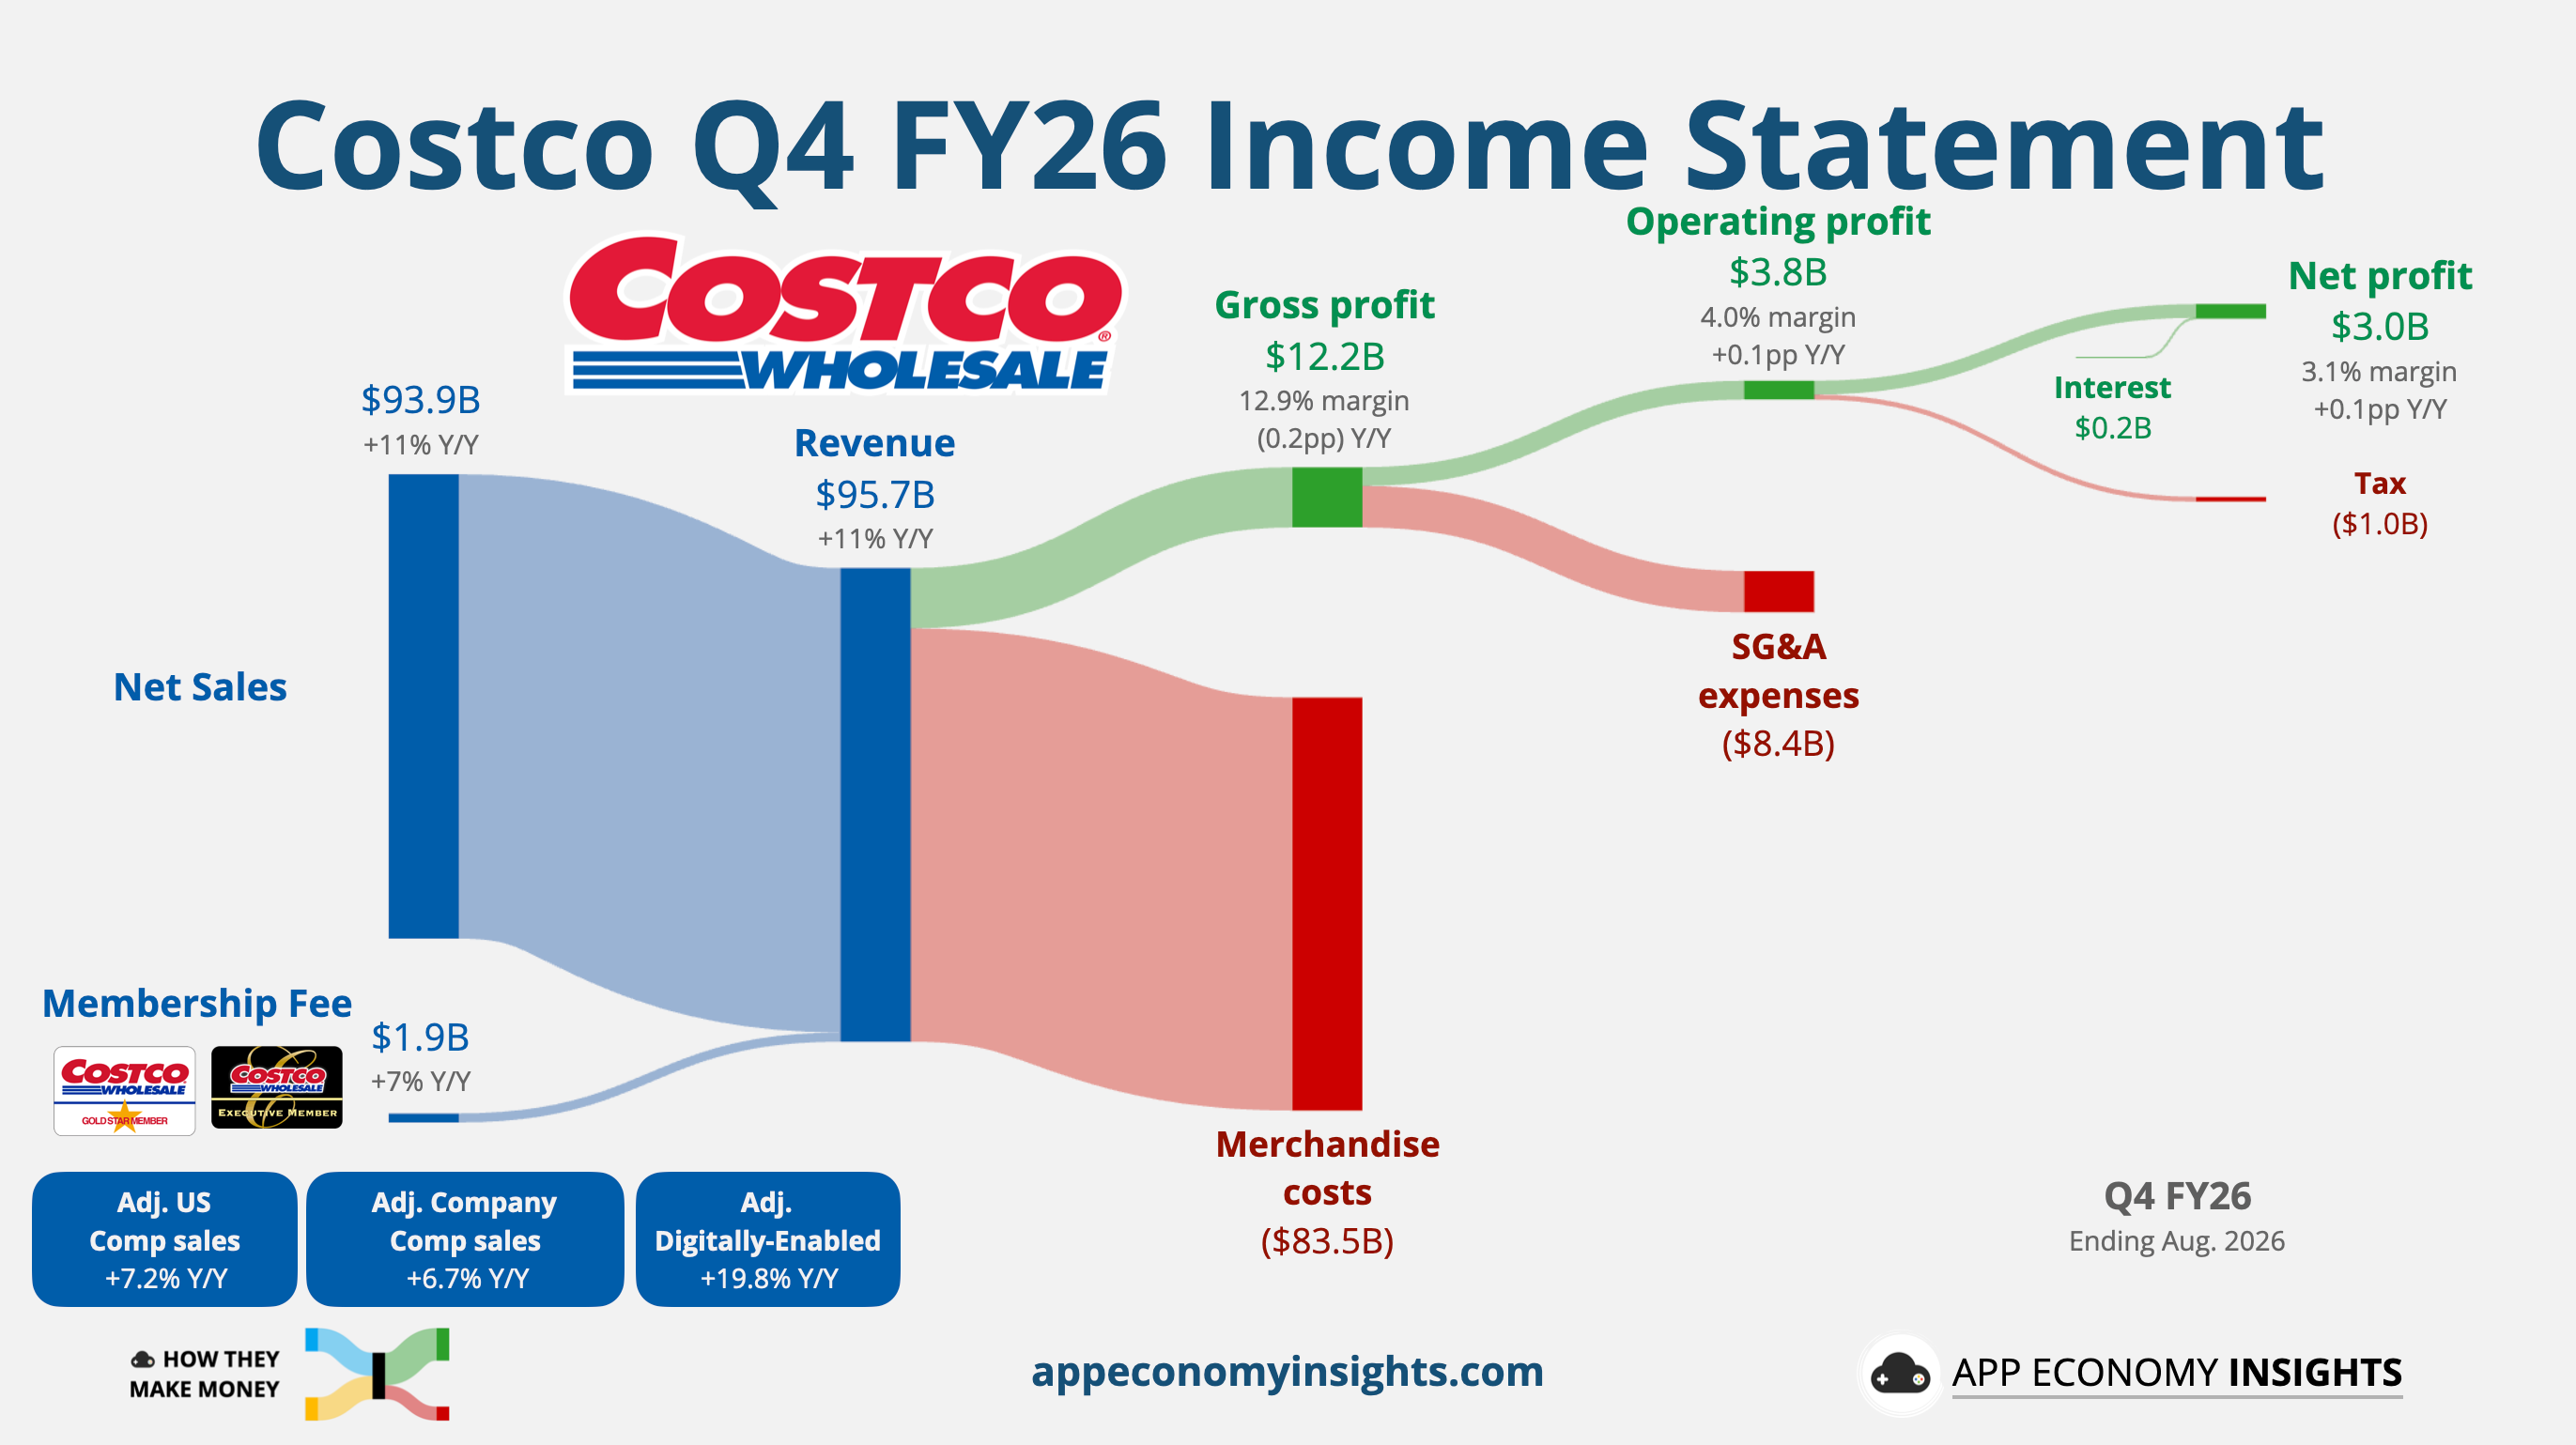
Costco received $184 million in tariff refunds during Q4 and reinvested part of that into lower prices across produce, meat, beverages, furniture, and other categories. Management already received a similar amount in Q1 and plans to return most future refunds to members through better value.
Membership remains healthy, but growth continues to normalize. Paid members increased 4% to 84.1 million, while Executive memberships grew 9% to 42.3 million. US/Canada renewal improved to 92.3%. Costco also plans 33 warehouse openings in FY27, accelerating from 25 net additions in FY26.
Consumer insights from Numerator data show that Costco’s recent household growth is skewing toward Gen Z and lower-income shoppers, while lower-income customers are already making fewer trips and spending less per basket.
The stock is still expensive. Costco’s forward P/E has fallen from above 50x at its peak to roughly 41x, but that still leaves little room for error.

Bottom Line: The gasoline boost still hasn’t normalized, but Costco’s core comps are holding around 7% anyway. With membership growth returning to a more normal pace, the next leg of growth increasingly depends on getting more from each member through digital, pharmacy, Executive upgrades, and a broader services ecosystem. The market is certainly counting on it.